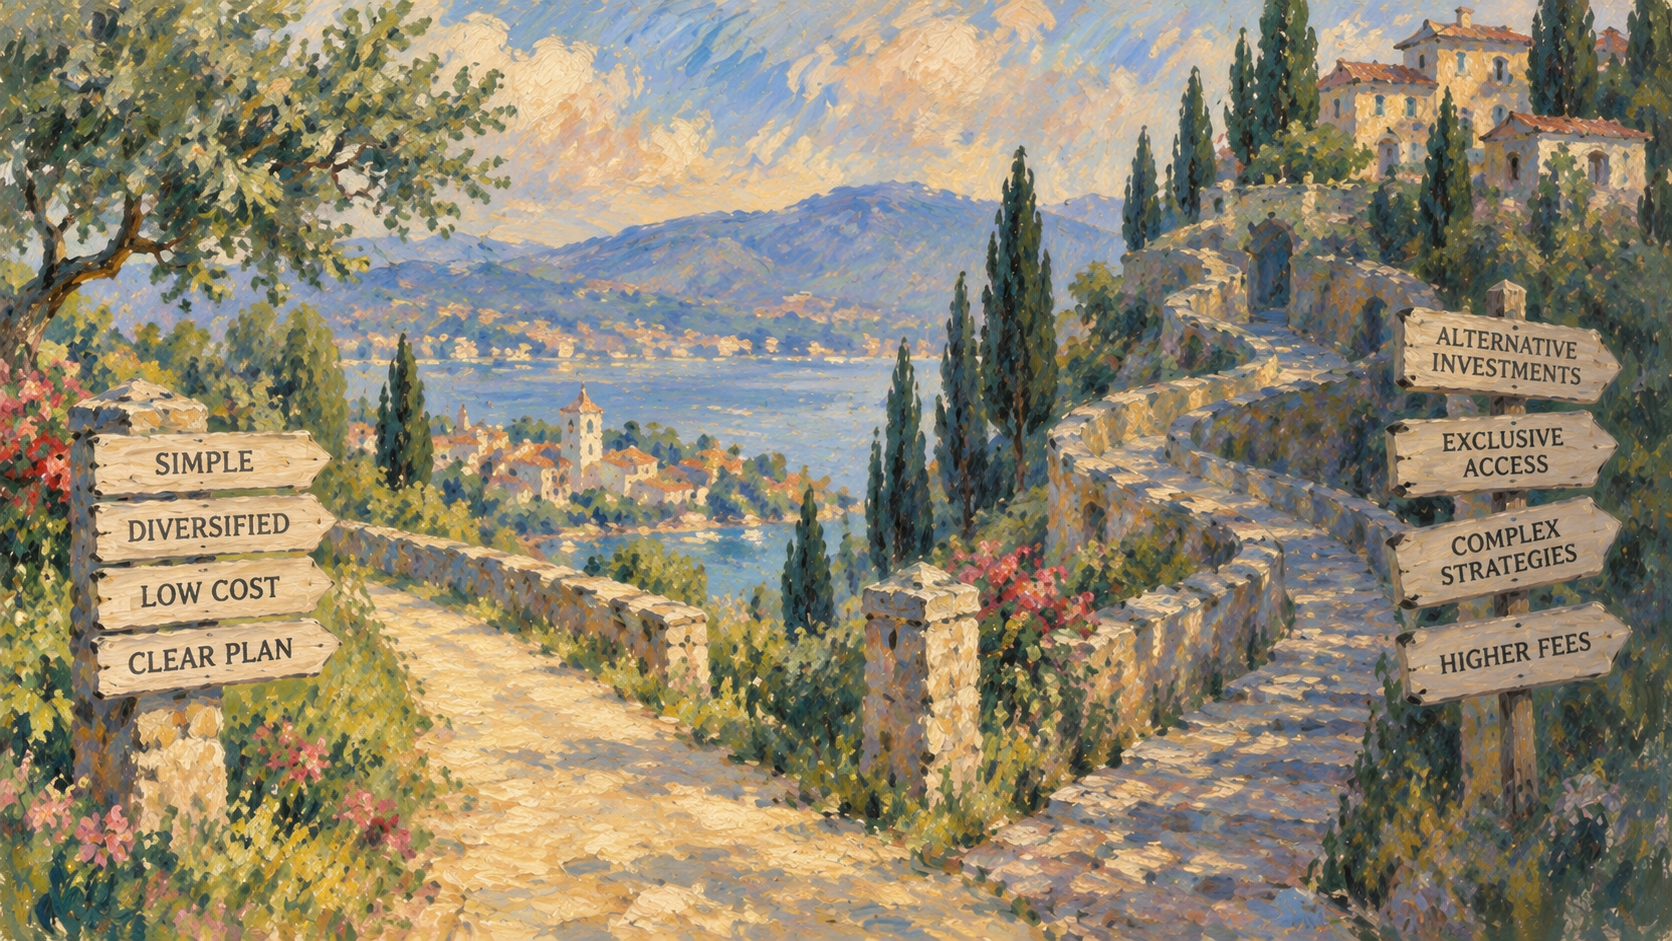
When someone sells their business, they suddenly become a very attractive prospect for the wealth management industry. The pitches are for broad diversification, many different (esoteric) asset classes, and other strategies. But once someone has a big portfolio, do they really need fundamentally different investments or are they simply receiving more sophisticated sales pitches?
A recent Canadian Family Offices interview with Thane Stenner illustrates this debate. In this commercial feature, Stenner recommends beginning with an investment policy statement. I agree. Establishing objectives, spending needs, risk tolerance and decision-making responsibilities is a sensible foundation.
My concern is with his suggestion that substantial wealth calls for exclusive strategies beyond a conventional portfolio. His sales pitch appeals to status and complexity bias: if you have exceptional wealth, surely you need exceptional investments.
Restricted access, however, doesn’t establish superior investment results. Neither does customization. An investment should earn its place in a portfolio based on what it contributes after fees, taxes and risk, not depending on how few people can buy it.
Stenner also recommends deploying capital over 12 to 24 months, citing expensive markets and the desire to avoid regret following a correction. To my ear, this framing turns an understandable investor bias into a sales advantage. It emphasizes the pain of investing before a decline while leaving the potential cost of waiting in the background.
That reassurance may help someone who would otherwise remain in cash. And its true there’s value in helping investors stay in productive assets. But such advice becomes less transparent when the emotional appeal is presented without the evidence needed to evaluate the trade-off.
For example, Vanguard’s research generally favours investing available capital immediately over temporarily holding some back. The evidence is clear, waiting or “legging into the market” is a losing strategy and leaves investors worse off. A transparent conversation would put that evidence up front: investing sooner generally offers a higher expected return, while a gradual approach may make the experience easier to tolerate emotionally. Lets be honest about the challenge, and be realistic about the emotional support a good advisor should provide.
The same scrutiny should apply to the assumption that greater wealth means greater complexity.
Wealthy families have high-stakes planning questions. But, those questions don’t necessarily require complicated answers. In my experience, the most successful long-term investors maintain a relatively simple approach to wealth management. They understand what they own, establish clear responsibilities and resist allowing unnecessary complexity to creep into their decisions and processes.
When the numbers are bigger, mistakes becomes even more costly. The same percentage mistake on $100 million produces ten times the dollar loss of a mistake on $10 million. That can make careful planning, independent review and professional support particularly valuable. It does not, by itself, make an elaborate portfolio necessary.
Some families do face genuinely complicated circumstances, including cross-border obligations, operating businesses or competing beneficiary needs. Those circumstances should drive the advice. The size of the account alone should not.
Professional advice can create considerable value by organizing information, identifying consequential choices and helping a family follow through consistently. Often, the best outcome of that work is greater simplicity: fewer moving parts, clearer decisions and a process the family understands.
Low-cost, diversified portfolios deserve consideration at every level of wealth. Any proposed departure should answer a straightforward question: What does this add, after all costs and risks, compared with a simpler alternative?
Good advice helps investors recognize their biases and understand their choices. Greater wealth makes that responsibility more consequential.